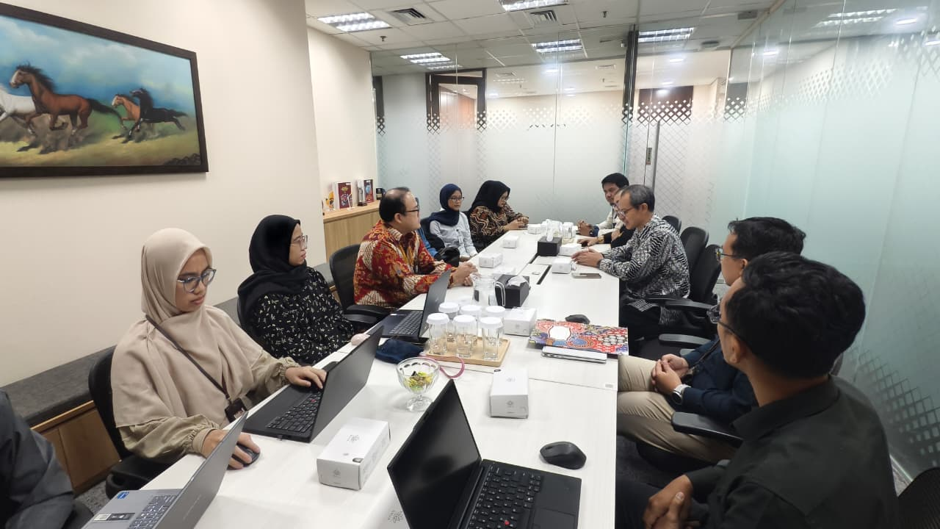

The Department of Statistics, Faculty of Science and Mathematics, Universitas Diponegoro, has established a research collaboration with PT Penilai Harga Efek Indonesia (PHEI), Price Valuation Unit, through an activity entitled “Study on the Revalidation of Corporate Bond Valuation Methodology,” held in Jakarta on Thursday, July 2, 2026. This activity represents a form of synergy between academia and industry in supporting the development of corporate bond valuation methodologies that are adaptive to financial market dynamics as well as advancements in statistical methods and data analysis.
The study aims to evaluate and revalidate corporate bond valuation methodologies to ensure their relevance to financial market developments, economic dynamics, and best practices in securities valuation. In addition to revalidating the existing methodologies, the research team is also exploring and developing alternative valuation models that have the potential to produce more accurate, robust, and market-relevant corporate bond price estimations in accordance with the characteristics of Indonesia’s bond market.
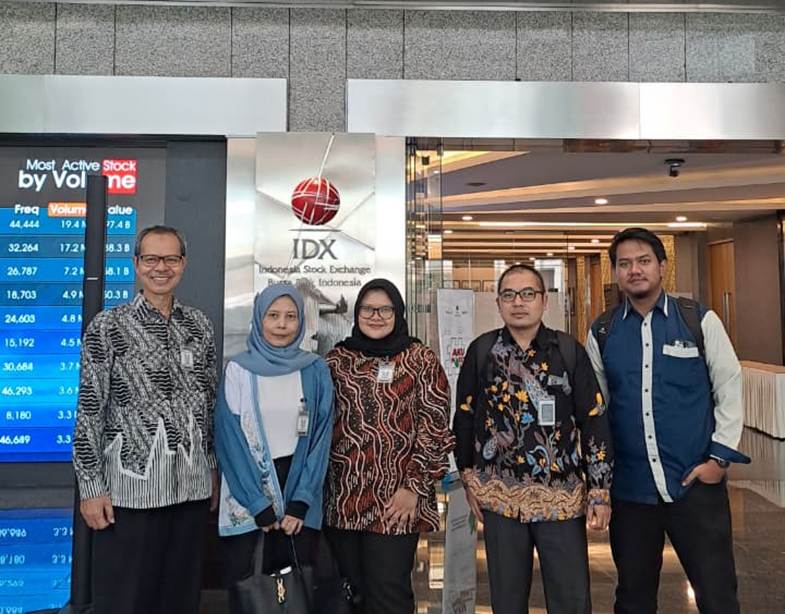
The research team from the Department of Statistics FSM UNDIP is led by Dr. Di Asih I Maruddani, S.Si., M.Si., with team members Prof. Tarno, M.Si., Dr. Abdul Hoyyi, M.Si., Dr. Hasbi Yasin, M.Si., Deby Fakhriyana, M.Stat., Rahmila Dapa, M.Sc., and Fariz Budi Arafat, M.Stats. Meanwhile, the team from PT Penilai Harga Efek Indonesia consists of Ifan Mohamad Ihsan and Ayu Ajeng Jayanti.
Through statistical approaches, quantitative modeling, and data analysis, various methods will be comprehensively evaluated to obtain the most optimal model for supporting the securities valuation process. The results of this study are expected to provide scientific recommendations for the development of corporate bond valuation methodologies while also supporting improvements in the quality, accuracy, transparency, and credibility of securities pricing processes in the Indonesian capital market.
This collaboration also reflects FSM UNDIP’s commitment to producing applied research that creates tangible impacts for industry, strengthens the implementation of statistical science in solving real-world problems, and supports the development of a more efficient and data-driven capital market ecosystem in Indonesia.